- New heavy goods vehicle registrations rise 7.2% with 9,941 new trucks reaching the road.
- First quarter of growth for two years and best market performance since Q3 2023.
- 50.7% slump in ZEV registrations demonstrates fragility of the transition and importance of a multi-technology approach to CO2 reduction
Data download
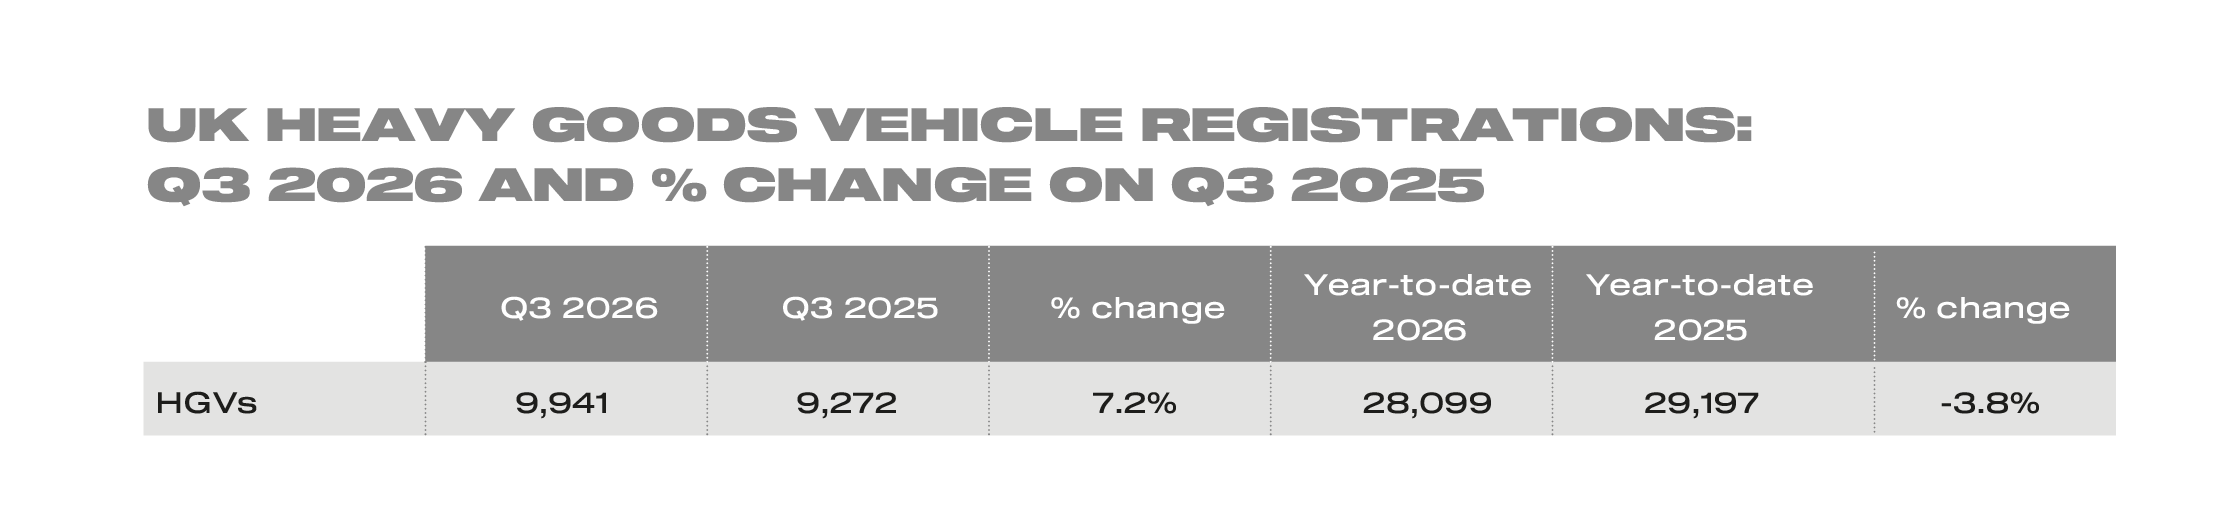
New HGV Registrations Q3 2026
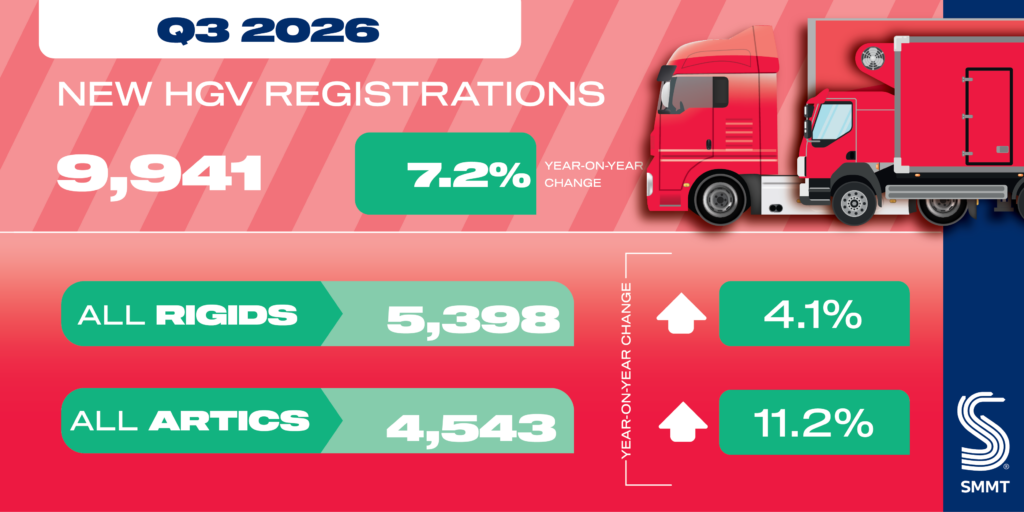
The new heavy goods vehicle (HGV) market returned to growth in the third quarter of 2026, up by 7.2% to reach 9,941 units, according to the latest figures published today by the Society of Motor Manufacturers and Traders (SMMT). The performance marked the first quarter of growth for the market since Q2 2024, and the strongest performance since Q3 2023.1
Uptake reflects the cyclical nature of HGV investment but is also flattered by comparison with the same period last year when registrations fell -14.5%. Despite the growth, the overall market remains -3.8% down year to date.
Although overall market demand increased, registrations of zero-emission HGVs halved in the quarter (-50.7%) to account for only 1.1% of the market. This is in comparison with a surge in Q3 last year when uptake quadrupled and market share hit 2.4%. Nevertheless, ZEV demand is down -30.9% in the year to date with just a 1.0% market share, demonstrating the considerable challenge of accelerating uptake despite a significant choice of models. The capital investment needed both to acquire vehicles and develop the depot infrastructure to support them remains a significant barrier, only in part lowered through government support from the Plug-in Truck Grant and Depot Charging Scheme. A national infrastructure strategy is also crucial to grow operator confidence, alongside a multi-technology approach to CO2 reduction – vital given the vast variety of use cases for HGVs.
Elsewhere in the market, demand for articulated trucks recovered, up 11.2% to reach 4,543 units, and returning this segment to overall growth year to date, up 2.3%. Rigid vehicle demand also increased in Q3, albeit by a more modest 4.1% to 5,398 units.
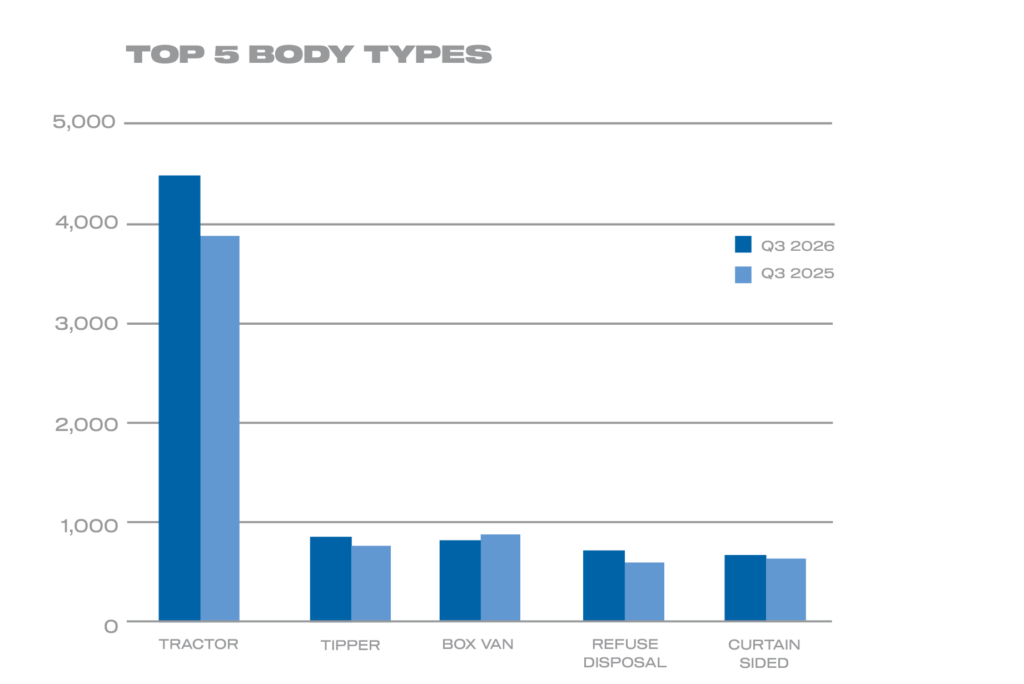
Tractor uptake improved by 12.3% to 4,453 units, with strong growth recorded by refuse disposal vehicles (up 31.5% to 760 units) and tippers (up 19.1% to 847 units), continuing the growth seen across the year. Curtain-sided trucks saw a smaller increase, up 8.4% to 657 units, while demand for box vans continued to fall, down -11.8% to 793 vehicles.
Across the UK, proportionally the greatest growth was seen in Northern Ireland, up 45.8%, although as one of the smallest markets in the UK, this represented a total of 328 deliveries. The largest volume increase was recorded in the South East, up 17.1% or 319 units with 2,187 new trucks reaching the road in a region home to both significant domestic economic output and cross-Channel haulage.
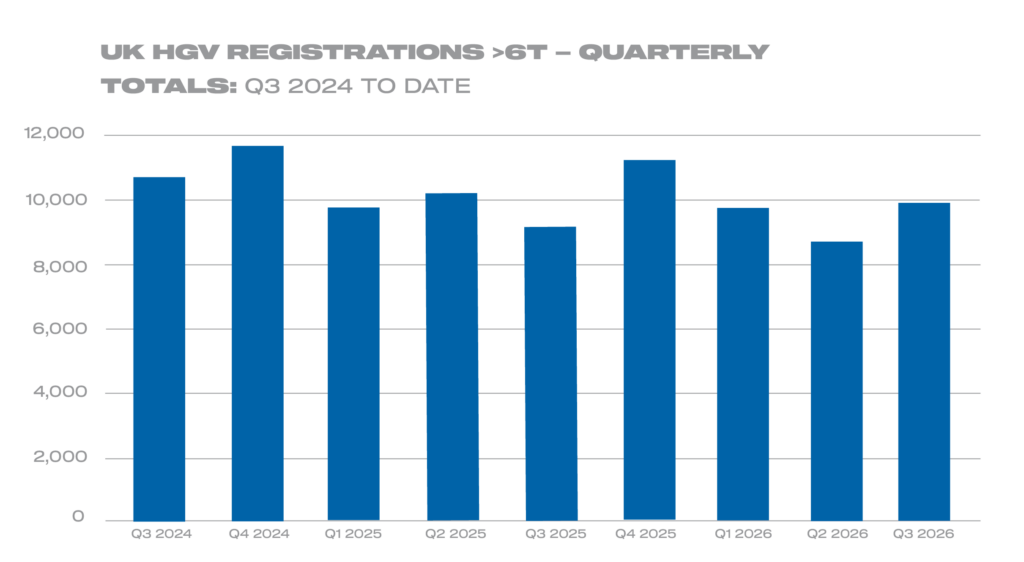
A recovery in new HGV registrations after two years of falling demand is a welcome boost for the sector, albeit from a low base. The decline in zero-emission registrations, however, underlines the volatility and fragility of the transition in a sector with complex operating requirements, with market share still stuck at just one in 100 new trucks. Accelerating decarbonisation will require action on all fronts: boosting operator confidence, removing barriers to investment and embracing every technology that can cut emissions on the road to a fully zero-emission market.
Notes to editors
- Q2 2024 growth: 2.6%; Q3 2023 growth: 16.4%.