The return to growth of the UK’s new heavy goods vehicle market in the third quarter of 2026 is a welcome sign of renewed confidence. Registrations rose 7.2% to 9,941 units, representing the strongest quarterly performance since Q3 2023, and the first increase since Q2 2024.
With the cyclical nature of HGV fleet investment programmes, the comparison follows a -14.5% fall in the same period last year, and the market remains -3.8% lower year to date. Even so, stronger demand across both articulated and rigid vehicles suggests operators are continuing to invest where business requirements support fleet renewal. Articulated truck registrations increased 11.2%, rigid vehicles rose 4.1% tractor registrations grew 12.3%.
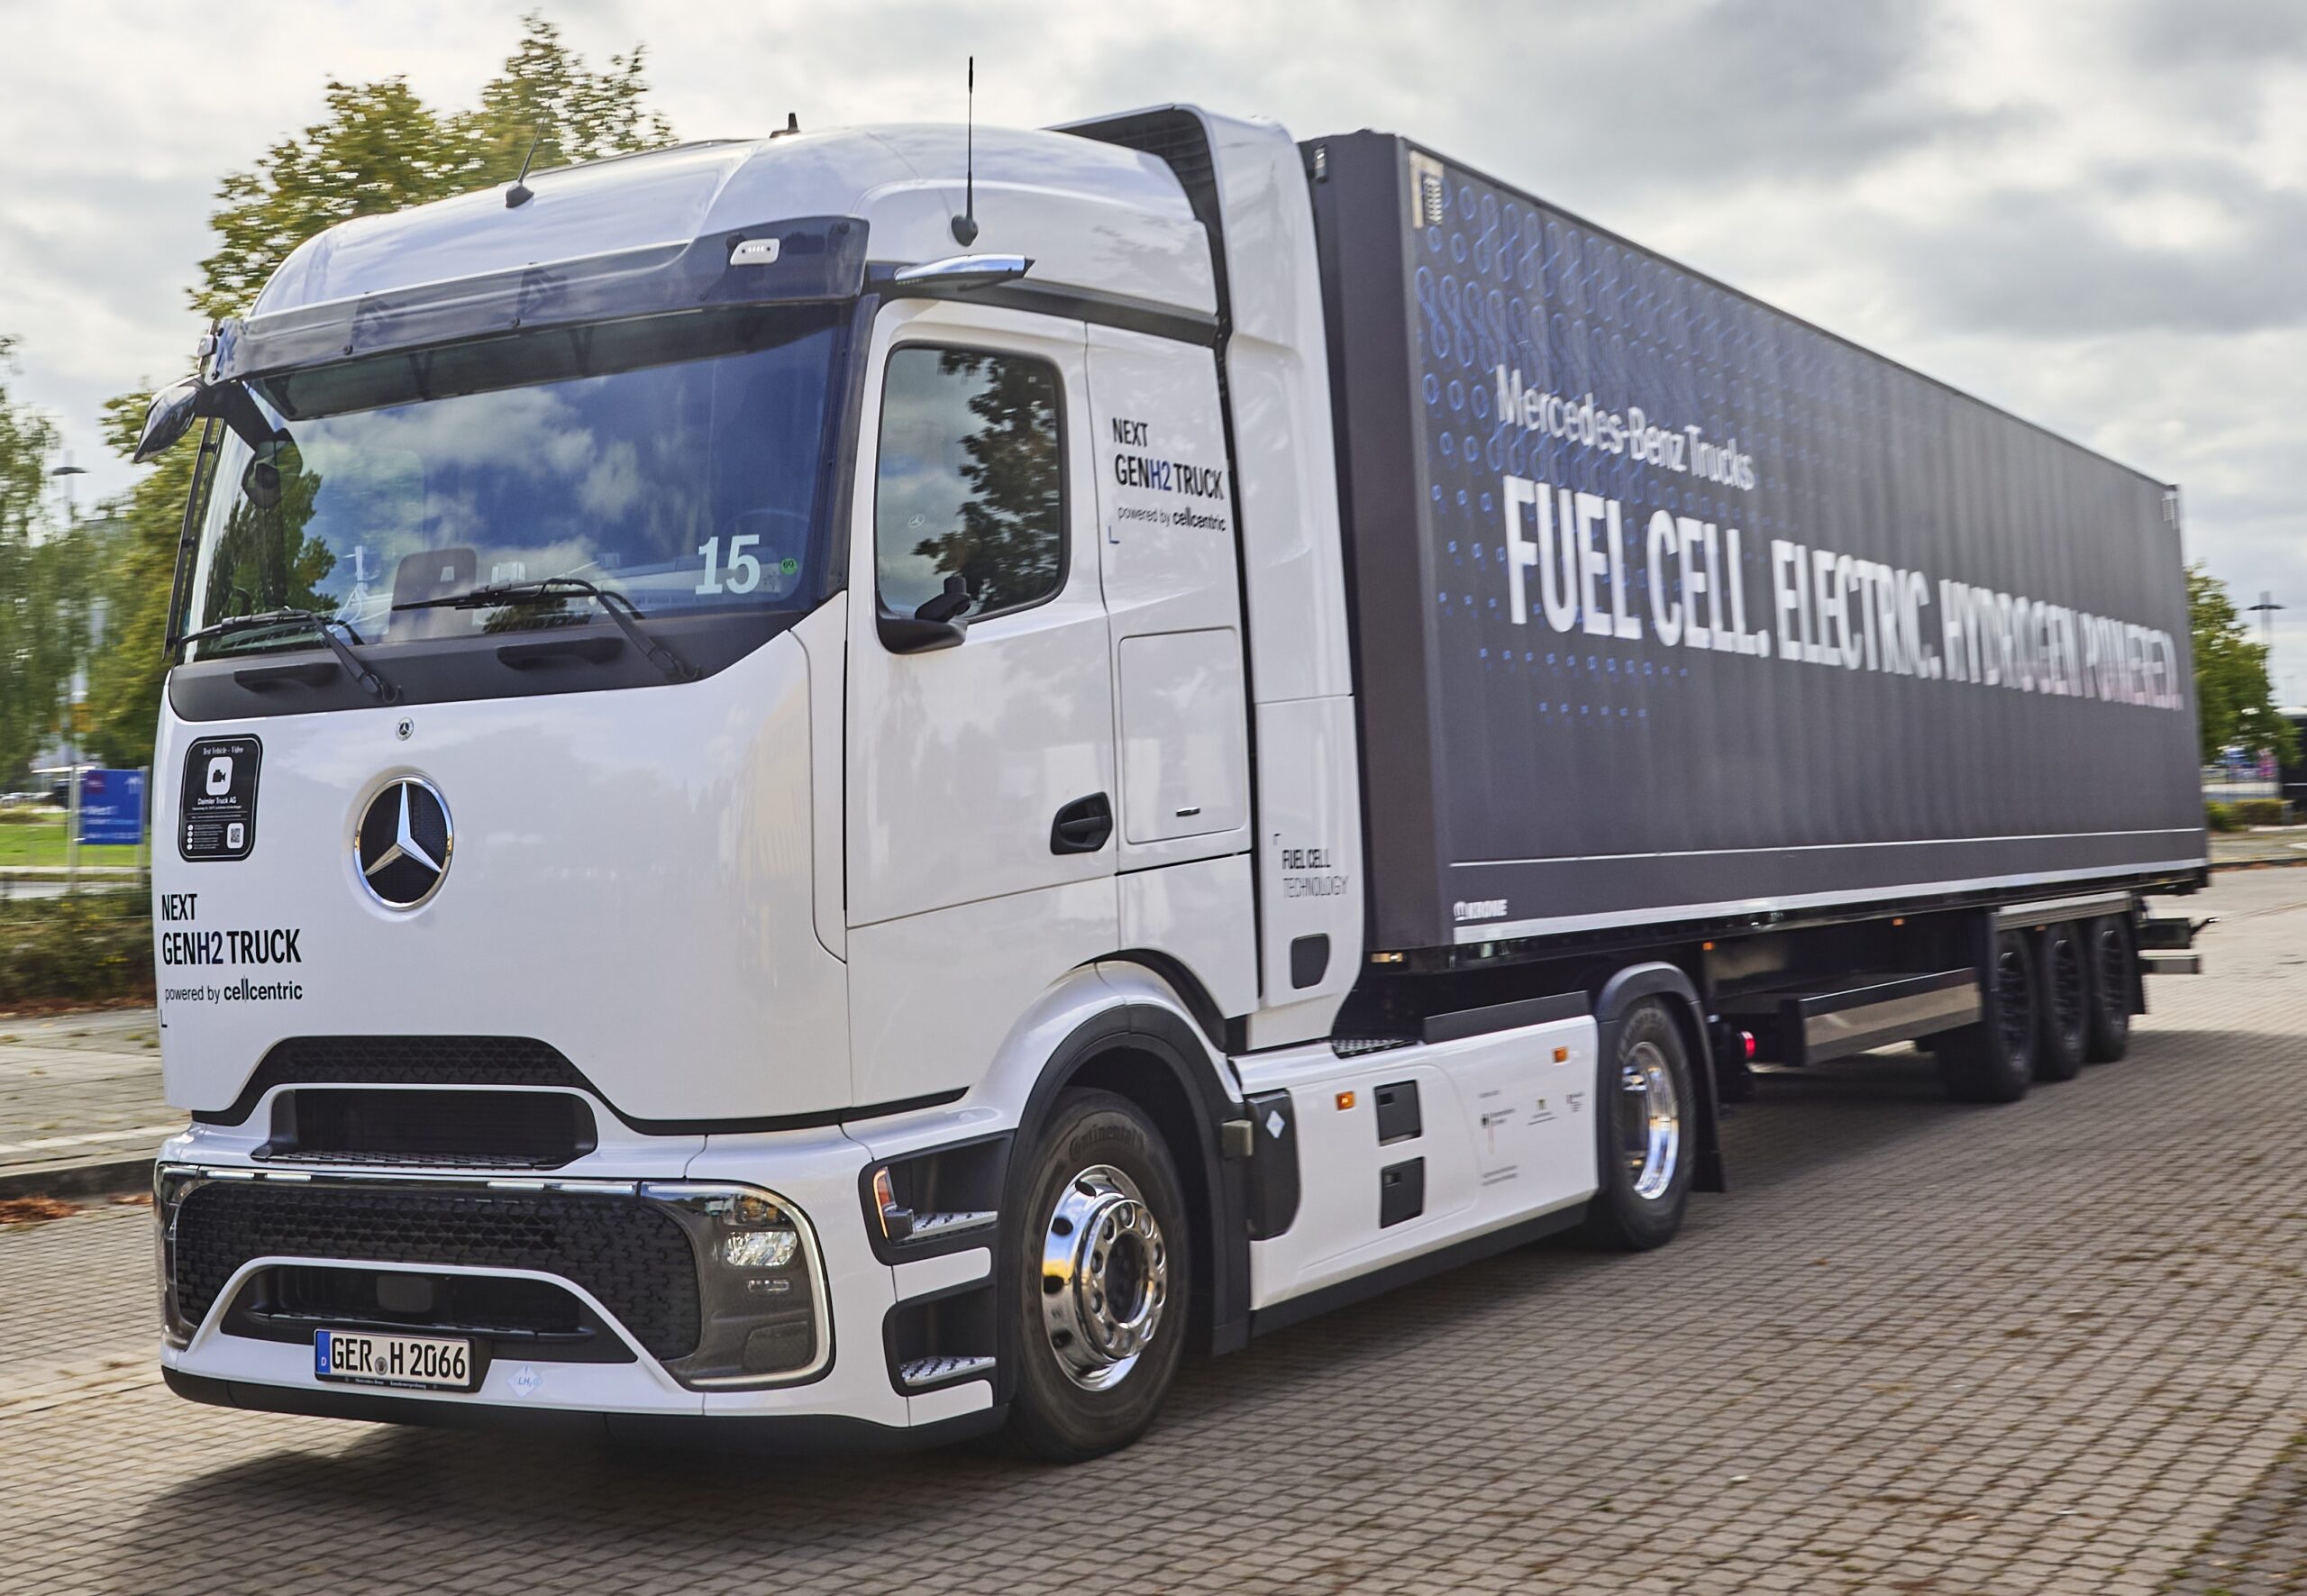
Registrations of zero emission HGVs fell -50.7% during the quarter, leaving these vehicles with just a 1.1% market share. Year-to-date demand is down 30.9%, despite manufacturers offering operators a significant and growing choice of models. This underlines that vehicle availability alone cannot deliver the transition. The drop in registrations demonstrates the need for continued incentives to support zero-emission HGV uptake, building on programmes such as the now concluded ZEHID, which helped overcome key barriers to adoption, including vehicle and infrastructure investment.
For HGV operators, the commercial case must work across an exceptionally diverse range of duties. The higher upfront cost of zero-emission vehicles, investment in depot charging infrastructure and uncertainty over access to reliable infrastructure all affect purchasing decisions. Existing measures, including the Plug-in Truck Grant and Depot Charging Scheme, are valuable foundations, but support must match the scale and complexity of the challenge.
A clear national infrastructure strategy would give operators greater confidence that vehicles can be charged or refuelled wherever their work takes them. At the same time, a pragmatic multi-technology approach to cutting CO₂ emissions is essential. Haulage, construction, municipal services and long-distance logistics have different operational needs, and the pathway must recognise those differences, and the tough investment environment which fleet operators are facing.